Is France Ready for an EU Taxpayer Bailout?
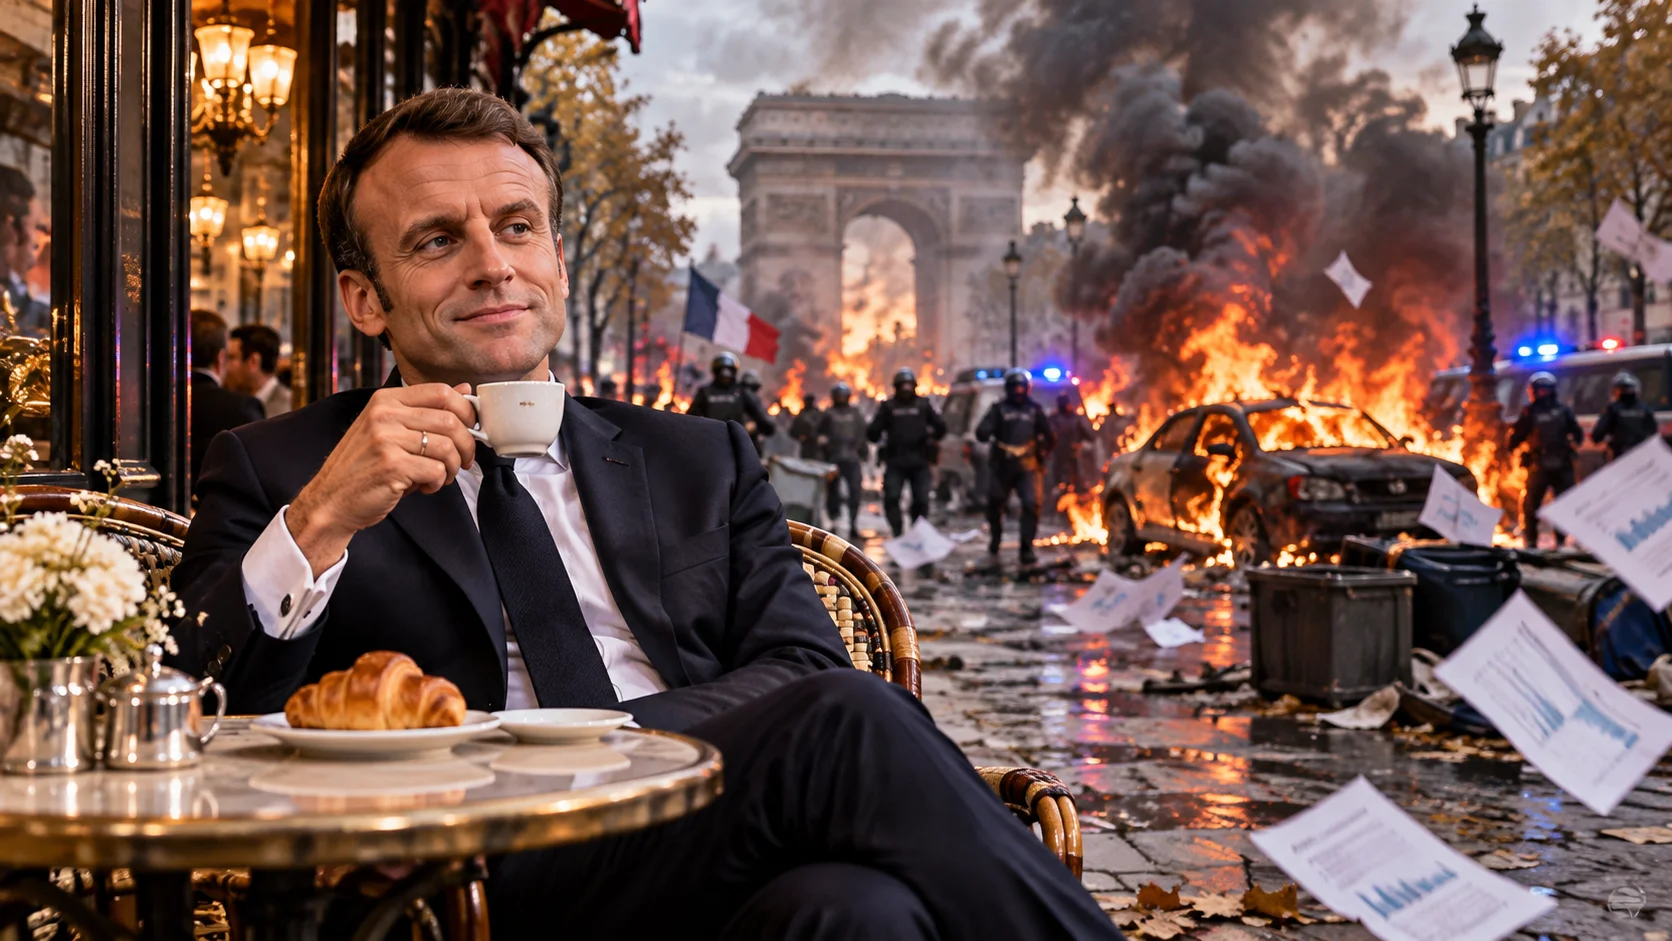
France's borrowing costs are climbing.
Its public debt reached €3.596 trillion, or 119% of GDP, by the end of June 2026. Its budget deficit remains around 5%, well above the European Union's 3% limit.
Yields on French ten-year government bonds approached 5% - France is now paying more to borrow than Greece and Italy.
The French government plans to issue a record €340 billion in bonds in 2027.
France didn't get here overnight. Macron's governments repeatedly missed deficit targets, tax revenues fell short, and attempts to reduce expenditure ran into political resistance.
Even after COVID emergency spending ended, France's deficit continued growing.
France now spends more than 57% of its GDP through the public sector, and even that isn't enough to pay its bills.
Financial analyst Bob Lyddon has calculated what a rescue could cost if the country loses access to financial markets.
His proposed solution? Have the European Union borrow the money and buy French debt.
Nobody would have to officially admit that France had been bailed out, of course.
Greece vs France
During the Greek debt crisis, Athens received emergency loans in exchange for austerity programmes, pension cuts, tax increases and years of economic hardship, while French and German bankers who had invested foolishly in Greek debt were protected.
The Greek people paid the bill.
Now France itself is facing a possible rescue operation.
The proposed answer is not to send European officials to Paris with a list of hospitals to close, but to have the European Union borrow €2 trillion. That's approximately €4,425 for every EU citizen, including children.
Of course, EU enlargement could help.
Add Ukraine and the Western Balkans, and the theoretical bill drops from €4,425 to around €3,933 per citizen.
Is this why the EU is so eager to expand?
Lyddon argues that the European Stability Mechanism (ESM), the eurozone's existing bailout fund, lacks the capacity for a rescue of this magnitude. He proposes that the other member states expose themselves to finance it.
France is also among the countries pushing to replace national vetoes with majority voting.
Broader EU reform proposals would extend majority voting into taxation and financial decisions.
Under that system, France's 68 million citizens give it considerably voting weight.
So while France may eventually need other Europeans to help finance its debts, the European Union is also discussing ways to make it easier to outvote smaller member states.
More people to share the bill. Fewer opportunities to say no.
European solidarity is a wonderful thing.
On July 6, we published The ECB's Golden Safety Net Is Starting to Look Thin: Who Will Pay the Next Greek-Style Bill?.
We examined the European Central Bank's financial position, Christine Lagarde's French and European political ambitions, the legacy of the Greek bailout and the possibility that the next serious financial crisis.
We wrote:
"When private investors are nervous, public money becomes brave. When public money is nervous, guarantees become innovative. When guarantees become inconvenient, the bill becomes European."
Three months later, we may have officially arrived.
If France needs rescuing, every European taxpayer should know what is being discussed here.
On the other hand - why would anyone care? It's only €2 trillion anyway.
Sources
You might also like